
Tax deadlines for reduction applications and interest on claims
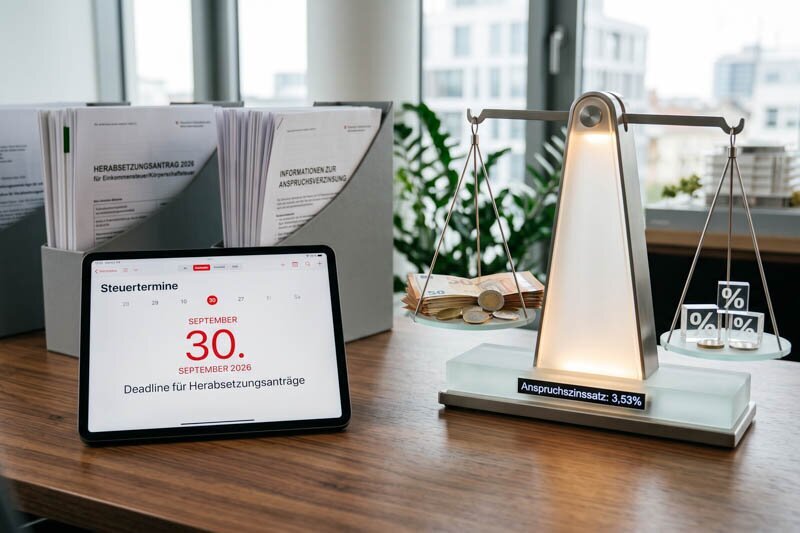
Important note: This article has been updated. Due to the increase in the base interest rate by the OeNB on September 16, 2026 from 1.53 % to 2.03 %, the relevant benchmark interest rate has also increased % from % 3.53 to 4.03.
Deadline for requests for reductions is September 30th
As every year, it is generally necessary to comply with the following deadlines by September 30, 2026, or by October 1, 2026:
Until at the latest September 30, 2026 (as provided for in the law), reduction requests for the 2026 advance payments for income and corporate tax can still be submitted to the competent tax authority. Key components of an application are a clear justification for the desired reduction of the advance payment, as well as a forecast calculation that can demonstrate the expected income. To avoid a late payment during the 2026 tax return or claim interest, the forecast calculation should at any rate be realistic.
Start and amount of claim interest from October 1st
The topic of claim interest: with effect from October 1, 2026, claim interest will begin to accrue for ESt or KSt claims for the tax year 2025 that are not yet properly filed at that time. Since the Base interest rate with effect % increased to 2.03 on September 16, 2026 was (previously 1.53 %), the resulting Claim interest rate now on 4,03 % – it is fixed at 2 % above the base interest rate. The claim interest compensates for interest gains or losses that arise from the later payment of the surcharge or the later effect of the credit, depending on the date of the tax assessment.
Avoidance of late payment interest and tax treatment
The problem of late payment interest (negative claim interest) can usually be avoided by paying a deposit to the tax office amounting to the expected late payment before October 1, 2026. If this has not been done so far, no charge will be incurred as long as the late payment interest does not exceed €50. Furthermore, claim interest can be fixed for a maximum period of 48 months – this is relevant, for example, if a multi-year appeal procedure is lost. To avoid claim interest, it may be advisable to make a corresponding payment to the tax office before the expiration of the „interest-free period“ that depends primarily on the expected late payment (the designation „E 1-12/2025“ or „K 1-12/2025“). However, claim interest accruing is not tax-deductible.
Interest on credit and credit on the tax account
Interest on claims can also be interest on refunds that are not subject to tax. Finally, it should be noted that excessive advance payments cannot generate interest, as balances such as arrears on the tax account are exempt from interest.
Image: Illustrative representation (generated by AI)
© ebit Steuerberatung GmbH | Client Information