
Short info: IFB expanded to climate-friendly heating systems
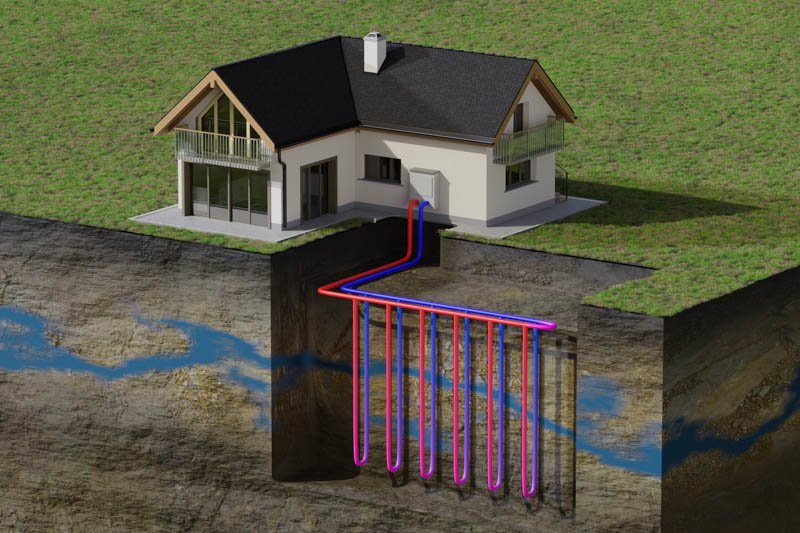
Following an amendment to Section 11 of the Income Tax Act (EStG) – the relevant section for the investment allowance (IFB) – it is now also possible to claim the investment allowance for the acquisition and production of climate-friendly heating systems in connection with buildings. This includes heat pumps, biomass boilers, district heating/cooling heat exchangers, district heating/cooling transfer stations, and micro-grids. Beyond the IFB, there are no further income tax implications, for instance, in the assessment of a heating system as a building component, e.g., for depreciation purposes. As is well known, the IFB is to be applied for the first time to assets acquired or produced after 31 December 2022.
Image: © Adobe Stock - vchalup
The published articles are protected by copyright and are provided without warranty.
© ebit Steuerberatung GmbH | Client Information
© ebit Steuerberatung GmbH | Client Information